The national business agenda this week is compact but consequential: the Bank of Canada will publish a summary of its recent policy meeting, three major public companies report quarterly results, and Statistics Canada will update the latest industry-level gross domestic product figures and advance estimates for the quarter.
Monetary policy transparency in focus
On Wednesday the Bank of Canada will release the summary of deliberations from its governing council’s July interest-rate decision. Earlier this month it left the policy rate unchanged at 2.25 per cent, noting the economy is showing signs of improvement and inflation is expected to moderate gradually from a recent spike.
Investors, economists and corporate treasurers will scan the summary for nuance on the central bank’s outlook for growth and inflation, guidance on future adjustments to the policy rate and any discussion of risks from trade, housing or labour markets. Markets typically react to fresh language that shifts the expected path of rates or highlights previously underemphasized risks.
Big corporate reports arrive midweek
Three major publicly traded Canadian firms have second-quarter results scheduled this week:
- Canadian Pacific Kansas City (CPKC) — results after markets close Wednesday. The railway recently set a monthly Canadian record in June, transporting 2.8 million metric tonnes of grain and grain products.
- Loblaw Cos. Ltd. — results before markets open Thursday. The grocer and pharmacy operator completed the sale of its PC Financial business to EQB Inc. earlier this year, a move that alters its financial-services footprint.
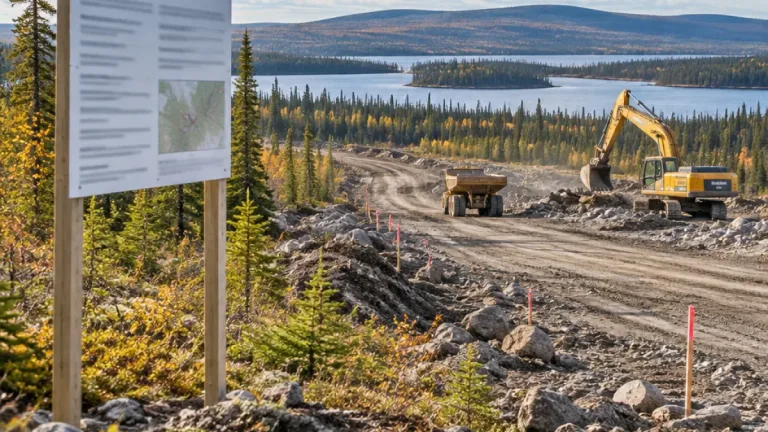
- Enbridge Inc. — results before markets open Friday. The energy infrastructure company has begun construction on a $4-billion natural gas pipeline expansion in British Columbia intended to add about 300 million cubic feet per day of capacity by installing roughly 140 kilometres of new pipe on its Westcoast system.
Each company’s results will be watched for revenue trends, margin pressures and capital-spending plans that could reverberate through supply chains and sector peers. For rail and energy firms, operating metrics — volumes moved, utilisation and pipeline throughput — often matter as much as headline earnings.
GDP-by-industry and the advance quarterly picture
On Friday, Statistics Canada will publish gross domestic product by industry for May and provide a preliminary reading for June and the second quarter. The agency’s advance estimate for May pointed to growth of 0.1 per cent, with gains in finance, insurance, real estate and rental and leasing partly offset by declines in wholesale trade and in agriculture, forestry, fishing and hunting.
The new release will give markets a clearer sense of which sectors are driving expansion as the quarter closes. Policymakers and investors use the detail to assess how durable growth is, where employment gains may be concentrated and which industries could feed inflationary pressure.
Why this week matters
Taken together, the central bank’s minutes, corporate earnings and the GDP breakdown provide a short but rich window into Canada’s economic momentum. The Bank of Canada summary could sharpen expectations about the path of rates; company reports will reveal demand and cost dynamics across transport, retail and energy; and the industry GDP numbers will identify the sectors underpinning growth.
| Event | Timing |
|---|---|
| Bank of Canada policy summary | Wednesday |
| CPKC Q2 results | Wednesday after markets close |
| Loblaw Q2 results | Thursday before markets open |
| Statistics Canada GDP by industry (May, preliminary June & Q2) | Friday |
| Enbridge Q2 results | Friday before markets open |
Market participants and corporate managers will be parsing these publications for signs of strength or softness that could affect hiring, investment and borrowing costs. With interest rates still materially above pre-pandemic norms and major firms reshaping their businesses — as seen in Loblaw’s disposal of PC Financial and Enbridge’s multi-billion-dollar pipeline project — the week’s releases could influence both short-term market moves and longer-term corporate strategies.